The neocloud debate is no longer just about demand for artificial intelligence. It is about the price of the computing itself—and whether that pricing can support the capital required to build the infrastructure.
Nebius is pushing back against bearish arguments about AI infrastructure economics by saying AI computing prices are rising. That claim matters because GPU-dependent cloud providers need more than hardware utilization; they need pricing power strong enough to withstand debt obligations, borrowing costs and the heavy capital demands of the business.
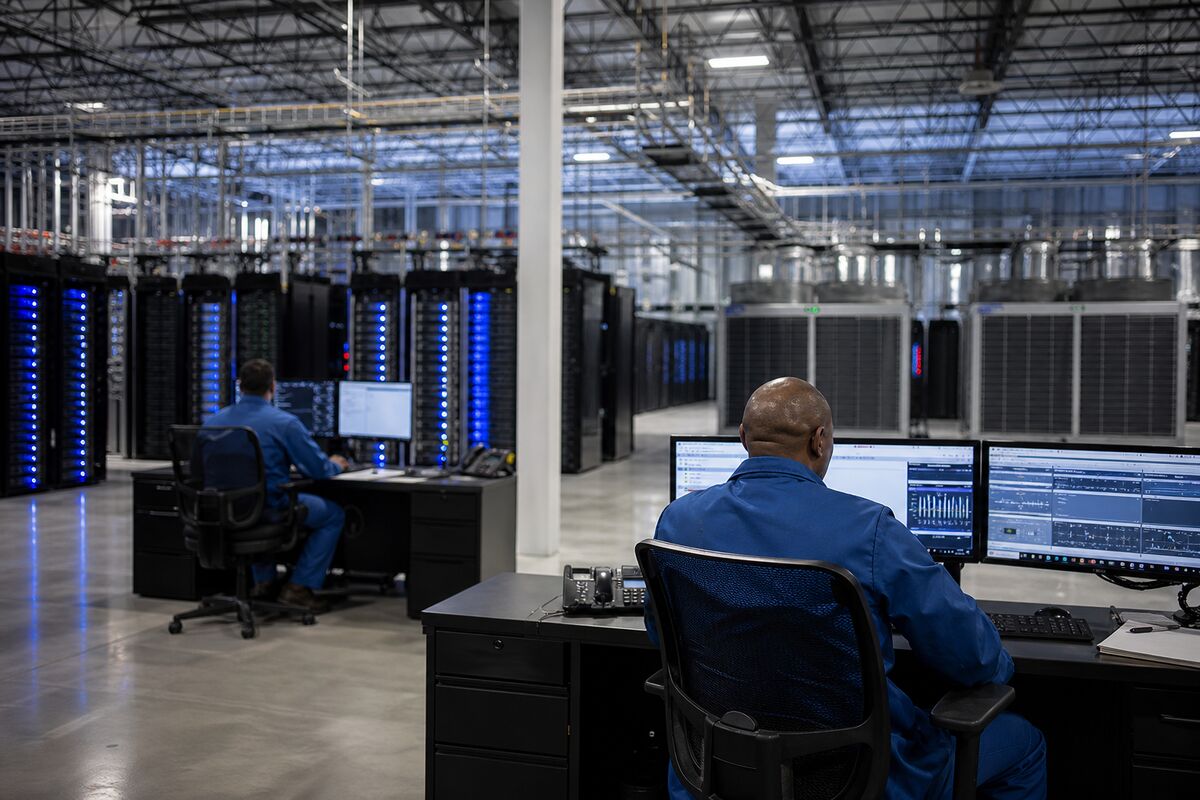
As reported by CNBC, Nebius’s position arrives as investors scrutinize the economics of companies building infrastructure for artificial intelligence. The market’s concern is straightforward: if neocloud providers must spend heavily on GPUs and related capacity, their business models may remain exposed to financing costs even when customer demand is substantial.
Why GPU pricing is the critical variable
GPU computing prices sit at the center of the investment debate. These systems are essential to the workloads that support artificial intelligence, making access to computing capacity a potentially valuable service. For cloud providers that depend on AI hardware, the price charged for that capacity can shape the entire economic picture.
Rising prices, if sustained, could improve the revenue potential of GPU-based infrastructure. They may also suggest that demand for AI computing remains strong enough to support higher rates. That is the core of Nebius’s challenge to the bearish narrative: the economics may look different if the value of computing capacity is increasing rather than moving lower.
But a pricing claim is not the same thing as a complete business-case validation. Investors still need to separate the price of computing from the cost of providing it. GPU acquisition, infrastructure development, financing and ongoing operating requirements all matter. Higher customer prices could help, but the effect on earnings capacity depends on how those prices compare with the full cost structure.
Debt and borrowing costs remain part of the equation
The market’s scrutiny of neocloud companies includes debt levels and borrowing costs for a reason. Building AI infrastructure requires capital before the resulting capacity can generate revenue. If financing costs rise, the burden on a hardware-dependent model may increase even when demand for computing remains healthy.
That creates several questions around Nebius and similar providers. How much capital is required to expand capacity? What are the financing costs attached to that expansion? Can higher GPU computing prices persist long enough to support the investment cycle? And how sensitive is the model to any change in demand, pricing or access to capital?
Those are not arguments that Nebius’s pricing claim is wrong. They are the broader questions that determine whether higher prices represent durable business-model strength or simply one favorable part of a more complicated calculation.
A sharper test for the AI infrastructure thesis
The wider investor debate over AI spending has often focused on whether demand justifies the enormous infrastructure buildout. Nebius’s response shifts attention toward pricing. That is a useful distinction. Strong demand is important, but the market also needs evidence that providers can price computing capacity in a way that supports their financing and operating commitments.
For traders and investors evaluating cloud providers tied to GPUs, the key issue is therefore not merely whether AI usage is expanding. It is whether computing prices, capital requirements and borrowing costs can remain aligned. Nebius’s statement offers a bullish data point on pricing, but it does not by itself settle the questions surrounding profitability, financing pressure or long-term durability.
That leaves the neocloud argument unresolved. The bears have a legitimate focus on debt and capital intensity. Nebius has offered a direct counterpoint: AI computing prices are rising. The next phase of the debate will turn on whether that pricing strength can persist and translate into a more durable economic model.
Bull/Bear Verdict
Bull Case: Nebius’s claim that AI computing prices are rising could indicate stronger pricing power for GPU-dependent infrastructure providers and may support the economics of continued AI capacity investment.
Bear Case: Higher computing prices may not resolve concerns about debt, borrowing costs and the capital intensity of neocloud models, leaving the durability of the business case uncertain.