GE Vernova is putting $9 billion behind the part of the AI story that rarely gets the glamorous headlines: the equipment needed to move electricity to where it is consumed. The proposed acquisition of grid-equipment maker Trench, paired with another increase to GE Vernova’s revenue forecast, gives industrial and infrastructure investors a more tangible way to think about data-center power demand.
The important point is not merely that GE Vernova is buying another business. It is that the company is adding grid equipment while continuing to raise its view of future revenue. (The machinery may be less photogenic than an AI model, but it is considerably harder to run a data center without it.) CNBC Investing Club’s Jim Cramer described GE Vernova as having “crushed it,” in a market discussion that also highlighted numbers from SK Hynix.
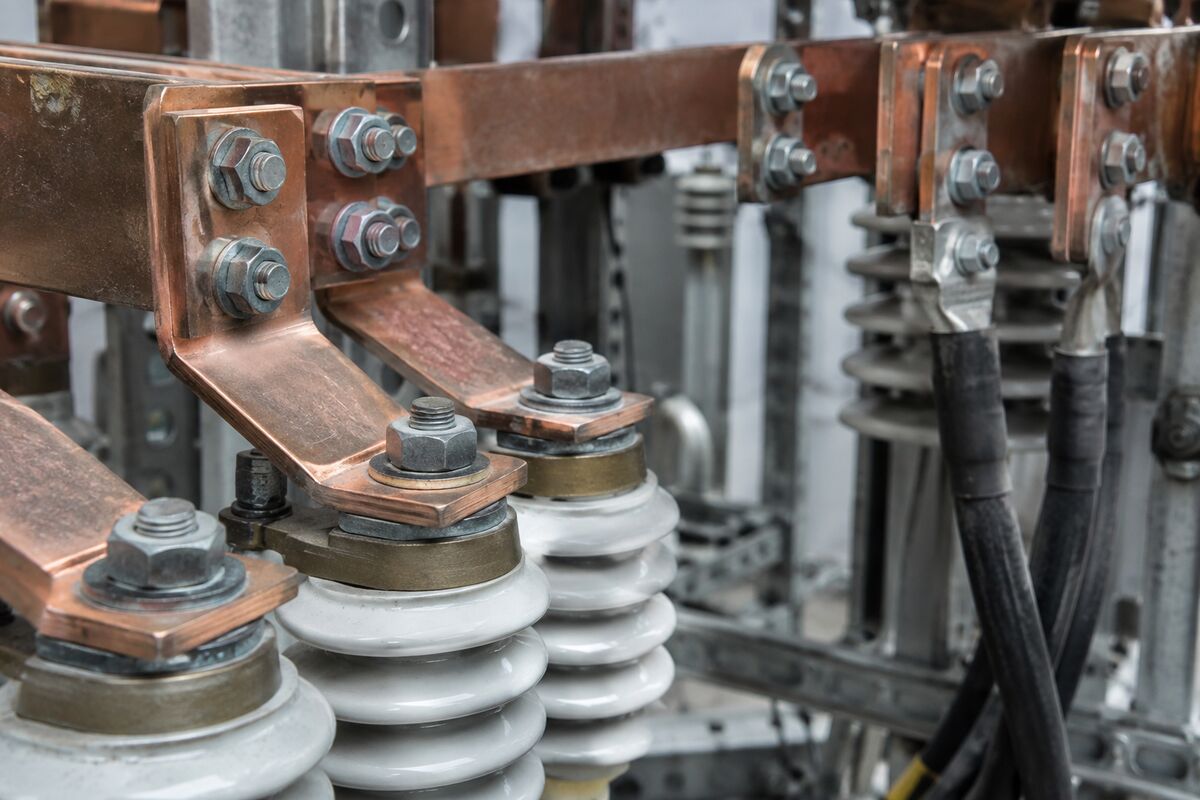
That combination puts the company squarely inside one of the market’s increasingly consequential industrial themes: power infrastructure connected to the buildout of AI data centers. The reported Trench transaction matters because grid equipment is the physical link between electricity generation, transmission and the facilities that require it.
The forecast matters as much as the deal
Acquisitions can be dressed up as strategy after the fact. A higher revenue forecast is harder to reduce to presentation language. GE Vernova has raised its revenue forecast again, suggesting that management sees enough underlying demand to revise its outlook upward rather than simply repeat the previous guidance.
That does not settle the investment case. It does, however, make the Trench deal more coherent. GE Vernova would be adding a grid-equipment maker at a moment when investors are focused on whether electricity infrastructure can keep pace with the requirements of AI data centers. The acquisition therefore appears aligned with the company’s existing exposure to power equipment and with a demand theme that extends beyond software spending.
For industrial investors, the attraction is the potential visibility that comes from equipment tied to essential infrastructure. For utility-focused investors, grid equipment is part of the spending chain required to support expanding electricity needs. For data-center investors, it is a reminder that computing capacity depends on a much larger physical system. None of that makes every infrastructure transaction compelling, but it does explain why GE Vernova’s announcement has drawn attention beyond the usual acquisition headline.
What the deal does and does not establish
The strategic rationale supplied by the facts is straightforward: Trench adds grid-equipment capability to GE Vernova while the parent is raising its revenue forecast. That combination may strengthen the company’s position in a power-infrastructure market receiving attention from industrial, utility and data-center investors.
What remains unresolved is everything that would determine whether the transaction ultimately creates value: the details of the acquisition, how the businesses would fit together and what the higher forecast implies for the company’s operating trajectory. Those questions are not answered by the $9 billion price tag or by a bullish remark on television.
Still, the broader signal is difficult to miss. The market’s AI enthusiasm is increasingly being translated into questions about electricity, grids and equipment. GE Vernova’s Trench proposal and renewed revenue-forecast increase offer a concrete example of that shift, while Cramer’s “crushed it” assessment shows how quickly the story has entered the conversation among market watchers. The next quarter’s real question is whether the higher forecast can keep turning infrastructure demand into sustained revenue growth, rather than merely validating the theme for another news cycle.
Bull/Bear Verdict
Bull Case: The $9 billion Trench acquisition may deepen GE Vernova’s grid-equipment position just as AI data-center power needs are drawing investor attention, while another revenue-forecast increase suggests demand could be broadening.
Bear Case: The higher forecast and strategic fit do not by themselves establish how the $9 billion deal will perform; without transaction and operating details, investors may still question whether the acquisition can translate the power-infrastructure theme into durable revenue growth.