Procter & Gamble’s first-quarter fiscal 2027 results offered investors something more useful than another declaration that consumers remain “resilient”: evidence. The company topped Wall Street’s estimates for both quarterly earnings and revenue, while sales rose 4%.
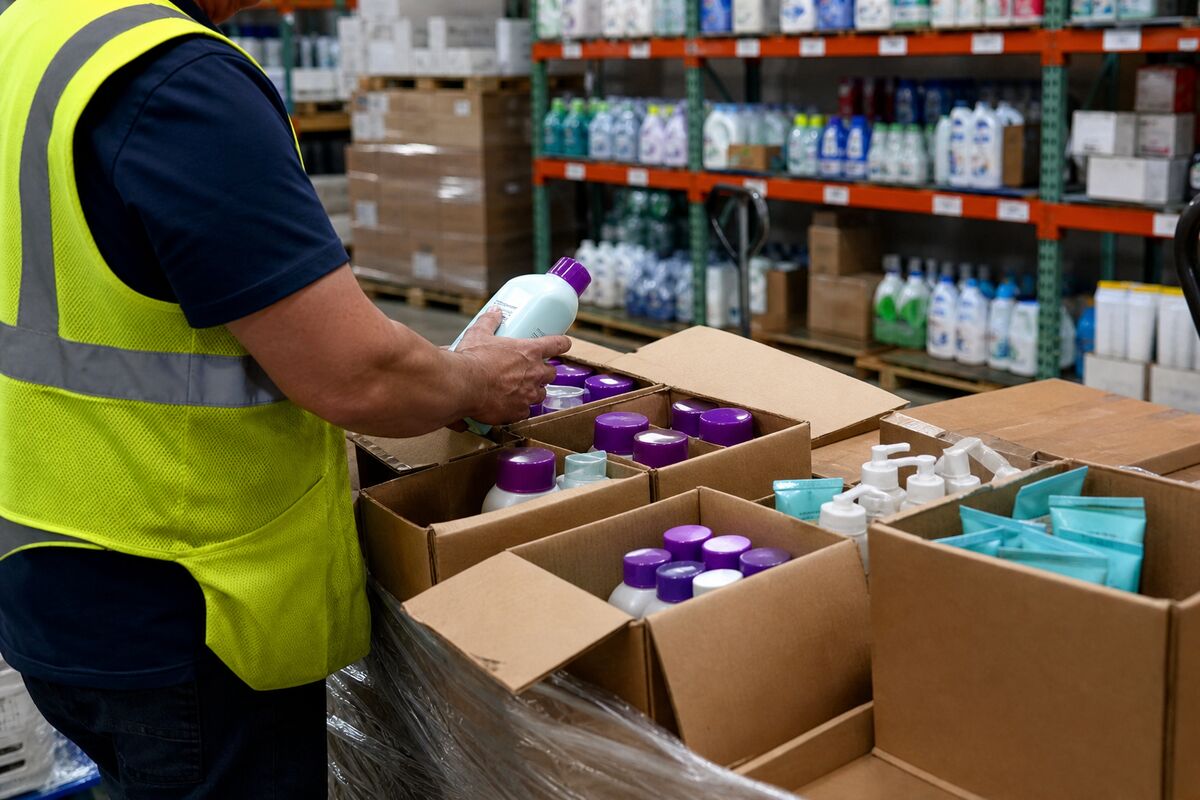
The growth was led by laundry and home products, categories that are not exactly glamorous but tend to remain stubbornly present in household budgets (which is less a shopping spree than a refusal to stop doing laundry). For investors watching inflation concerns and consumer spending, that combination—an earnings beat, a revenue beat and positive sales growth—makes $PG a timely test of whether defensive demand is holding up as the holiday quarter approaches.
As a major NYSE-listed consumer staples company and a Dow component, Procter & Gamble is often treated as a barometer for the less discretionary side of the economy. Its products are embedded in routine purchases, which can make the business less exposed to abrupt changes in consumer mood than companies dependent on large, postponable purchases. That does not make demand immune to pressure. It does mean the quarterly numbers can help distinguish between consumers becoming more selective and consumers pulling back altogether.
The beat matters, but the composition matters more
Set aside the prepared remarks for a moment: the important fact here is not simply that P&G cleared expectations. It is where the reported sales growth came from. Laundry and home products provided the main lift, suggesting that everyday household demand remained sufficiently durable to support 4% sales growth despite the backdrop of inflation concerns.
That is a meaningful signal for the defensive-stock argument. Defensive companies are not supposed to deliver excitement; they are supposed to demonstrate that ordinary demand can keep moving when the broader consumer picture becomes harder to read. P&G’s quarter indicates that at least some household essentials continue to occupy a protected place in spending.
Of course, the catch is that a single quarter does not settle the consumer question. A revenue beat can show that demand exceeded expectations without proving that purchasing power has fully recovered or that pressure on households has disappeared. The result is encouraging, but it is not a license to turn one quarter into an economic forecast.
What it says ahead of the holiday quarter
The timing gives the report added relevance. Heading into the holiday quarter, investors will be looking for evidence that consumers can sustain spending while managing inflation concerns. P&G’s results suggest the baseline for household essentials remains firm, particularly in laundry and home products.
That may support the case for defensive sectors when investors want exposure to consumer demand without relying entirely on discretionary spending. But the next quarter has to answer a more precise question: can P&G maintain the combination of sales growth and earnings outperformance, or did this quarter reflect a particularly favorable mix of essential purchases?
The bull case is straightforward. P&G beat estimates on both earnings and revenue, and 4% sales growth led by laundry and home products suggests everyday demand may be holding up better than the inflation narrative implies. The bear case is equally reasonable: one strong quarter does not establish a trend, and the results do not by themselves show whether consumer pressure is easing or simply being absorbed in routine purchases. The next report will have to provide that distinction.
For the full quarterly details, CNBC’s coverage of P&G’s Q1 fiscal 2027 results provides the source report.
Bull/Bear Verdict
Bull Case: P&G’s beat on both quarterly earnings and revenue, alongside 4% sales growth led by laundry and home products, may indicate that household essentials remain resilient despite inflation concerns.
Bear Case: The results may show only that routine purchases held up for one quarter; investors still need to see whether P&G can sustain sales growth and earnings outperformance through the holiday quarter.