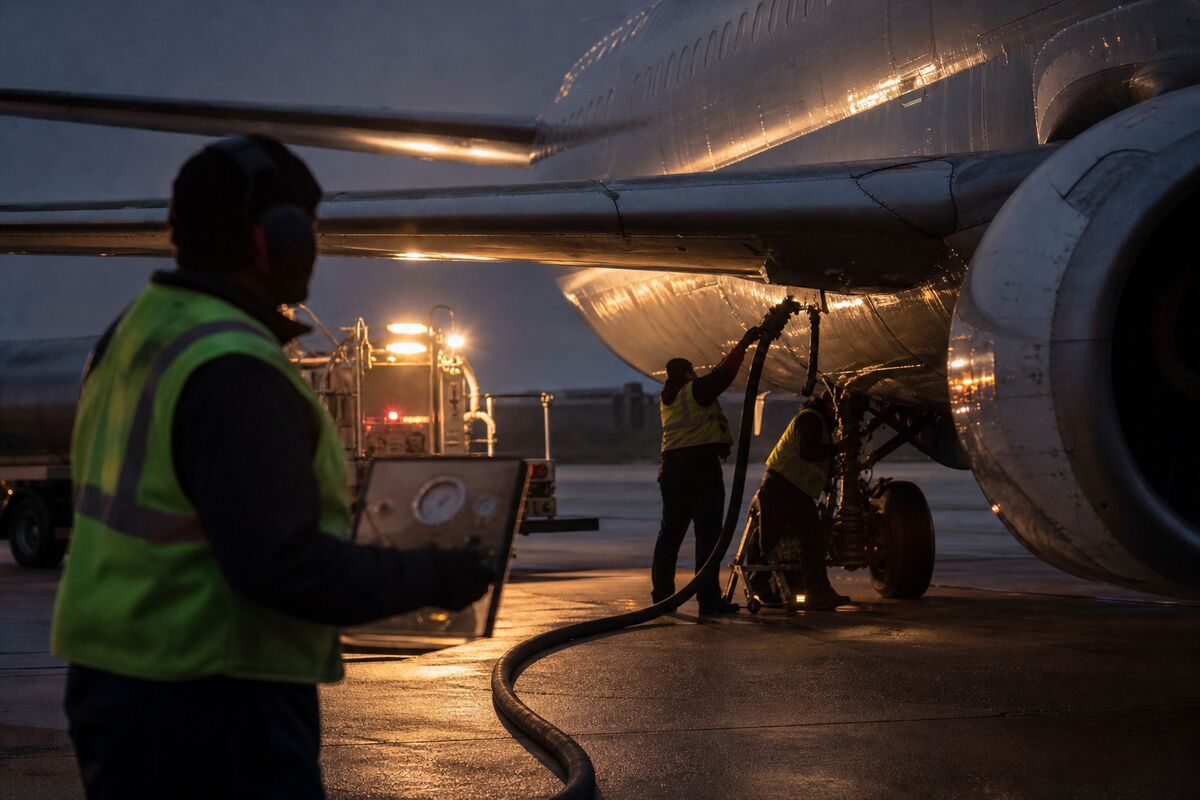
United Airlines lowered its 2026 earnings outlook because fuel costs are rising, but the more revealing part of its Q3 report is what did not break: travel demand. The company said customers continue booking flights despite higher fares, leaving investors with an inconvenient split-screen view of the airline business.
Bookings remain resilient. Margins are not. That is the central issue in United’s latest report, and it matters beyond $UAL because the carrier is a useful read on how airlines may handle an energy-cost shock heading into the holiday travel season.
According to United Airlines’ Q3 2026 earnings report, the company cut its 2026 outlook as rising fuel prices weighed on its expectations. Management’s message was not that passengers have suddenly disappeared. It was that the cost of carrying them has become more difficult to absorb.
Demand is holding. The arithmetic is deteriorating.
That distinction is important for traders. A demand collapse would point to a problem with fares, capacity, or consumer willingness to travel. United’s comments suggest something different: travelers are still booking even as fares rise, but higher ticket prices may not be enough to offset surging energy costs.
In other words, the airline can preserve revenue momentum while still losing ground on margins. Revenue resilience is useful; it is not a substitute for cost control. The report’s tension is straightforward: passengers appear willing to pay more, while fuel may be taking an increasing share of every fare. The phrase “resilient bookings” sounds reassuring until the expense line gets its turn.
Of course, the catch is that stronger demand does not automatically translate into stronger earnings. Fuel is a largely unavoidable operating cost, and the report frames the guidance reduction as a margin-pressure issue tied to rising energy prices. Middle East tensions and higher oil prices have added to that pressure, making fuel inflation a sector-wide concern rather than a problem unique to United.
Why the guidance cut matters for airline stocks
For the broader airline sector, United’s update raises a practical question: how much of the industry’s holiday-season demand can be converted into earnings if fuel costs continue moving higher? The answer will depend on the balance between fares, bookings, and expenses. Strong travel demand may give carriers pricing power, but pricing power has limits if fuel inflation accelerates faster than ticket prices.
That is why the outlook reduction deserves more attention than a simple demand headline. The company is not describing empty planes or a sudden retreat by travelers. It is warning that the economics of serving those travelers have worsened. For airline stocks, that may mean the market pays less attention to booking volume alone and more attention to whether carriers can protect margins while maintaining demand.
United’s report therefore offers a mixed signal heading into the holidays. Consumers appear willing to keep flying despite higher fares, which supports the demand side of the story. But rising fuel prices could absorb the benefit, especially if the cost pressure persists through the period when airlines are relying on travel volume to support results.
The next quarter’s actual question is not whether people still want to travel. United has already suggested that they do. It is whether fares can keep pace with energy costs well enough to prevent resilient bookings from becoming a margin problem in disguise.
Bull/Bear Verdict
Bull Case: Continued bookings despite higher fares may indicate that travel demand remains strong enough for United to pass through at least some cost increases, supporting the airline’s holiday-season earnings outlook if fuel pressure eases.
Bear Case: The 2026 outlook cut indicates that rising fuel prices are already pressuring margins, and further oil-price inflation could overwhelm the benefit of resilient bookings across airline stocks.